Westways Financial and the New Shape of Mortgage Advice
The mortgage market has become a harder place to make ordinary decisions. Buying a first home, refinancing at the right time or moving up the ladder still sounds like progress, but the process itself has become more demanding: tighter affordability checks, changing lender criteria, longer chains of communication and a level of admin that can quickly turn a milestone into a source of strain. For many borrowers, the challenge is no longer just finding a mortgage. It is understanding what is right for them, what will stand up under pressure and what will still make sense once the move is done. In that kind of market, advice carries more weight than it once did.
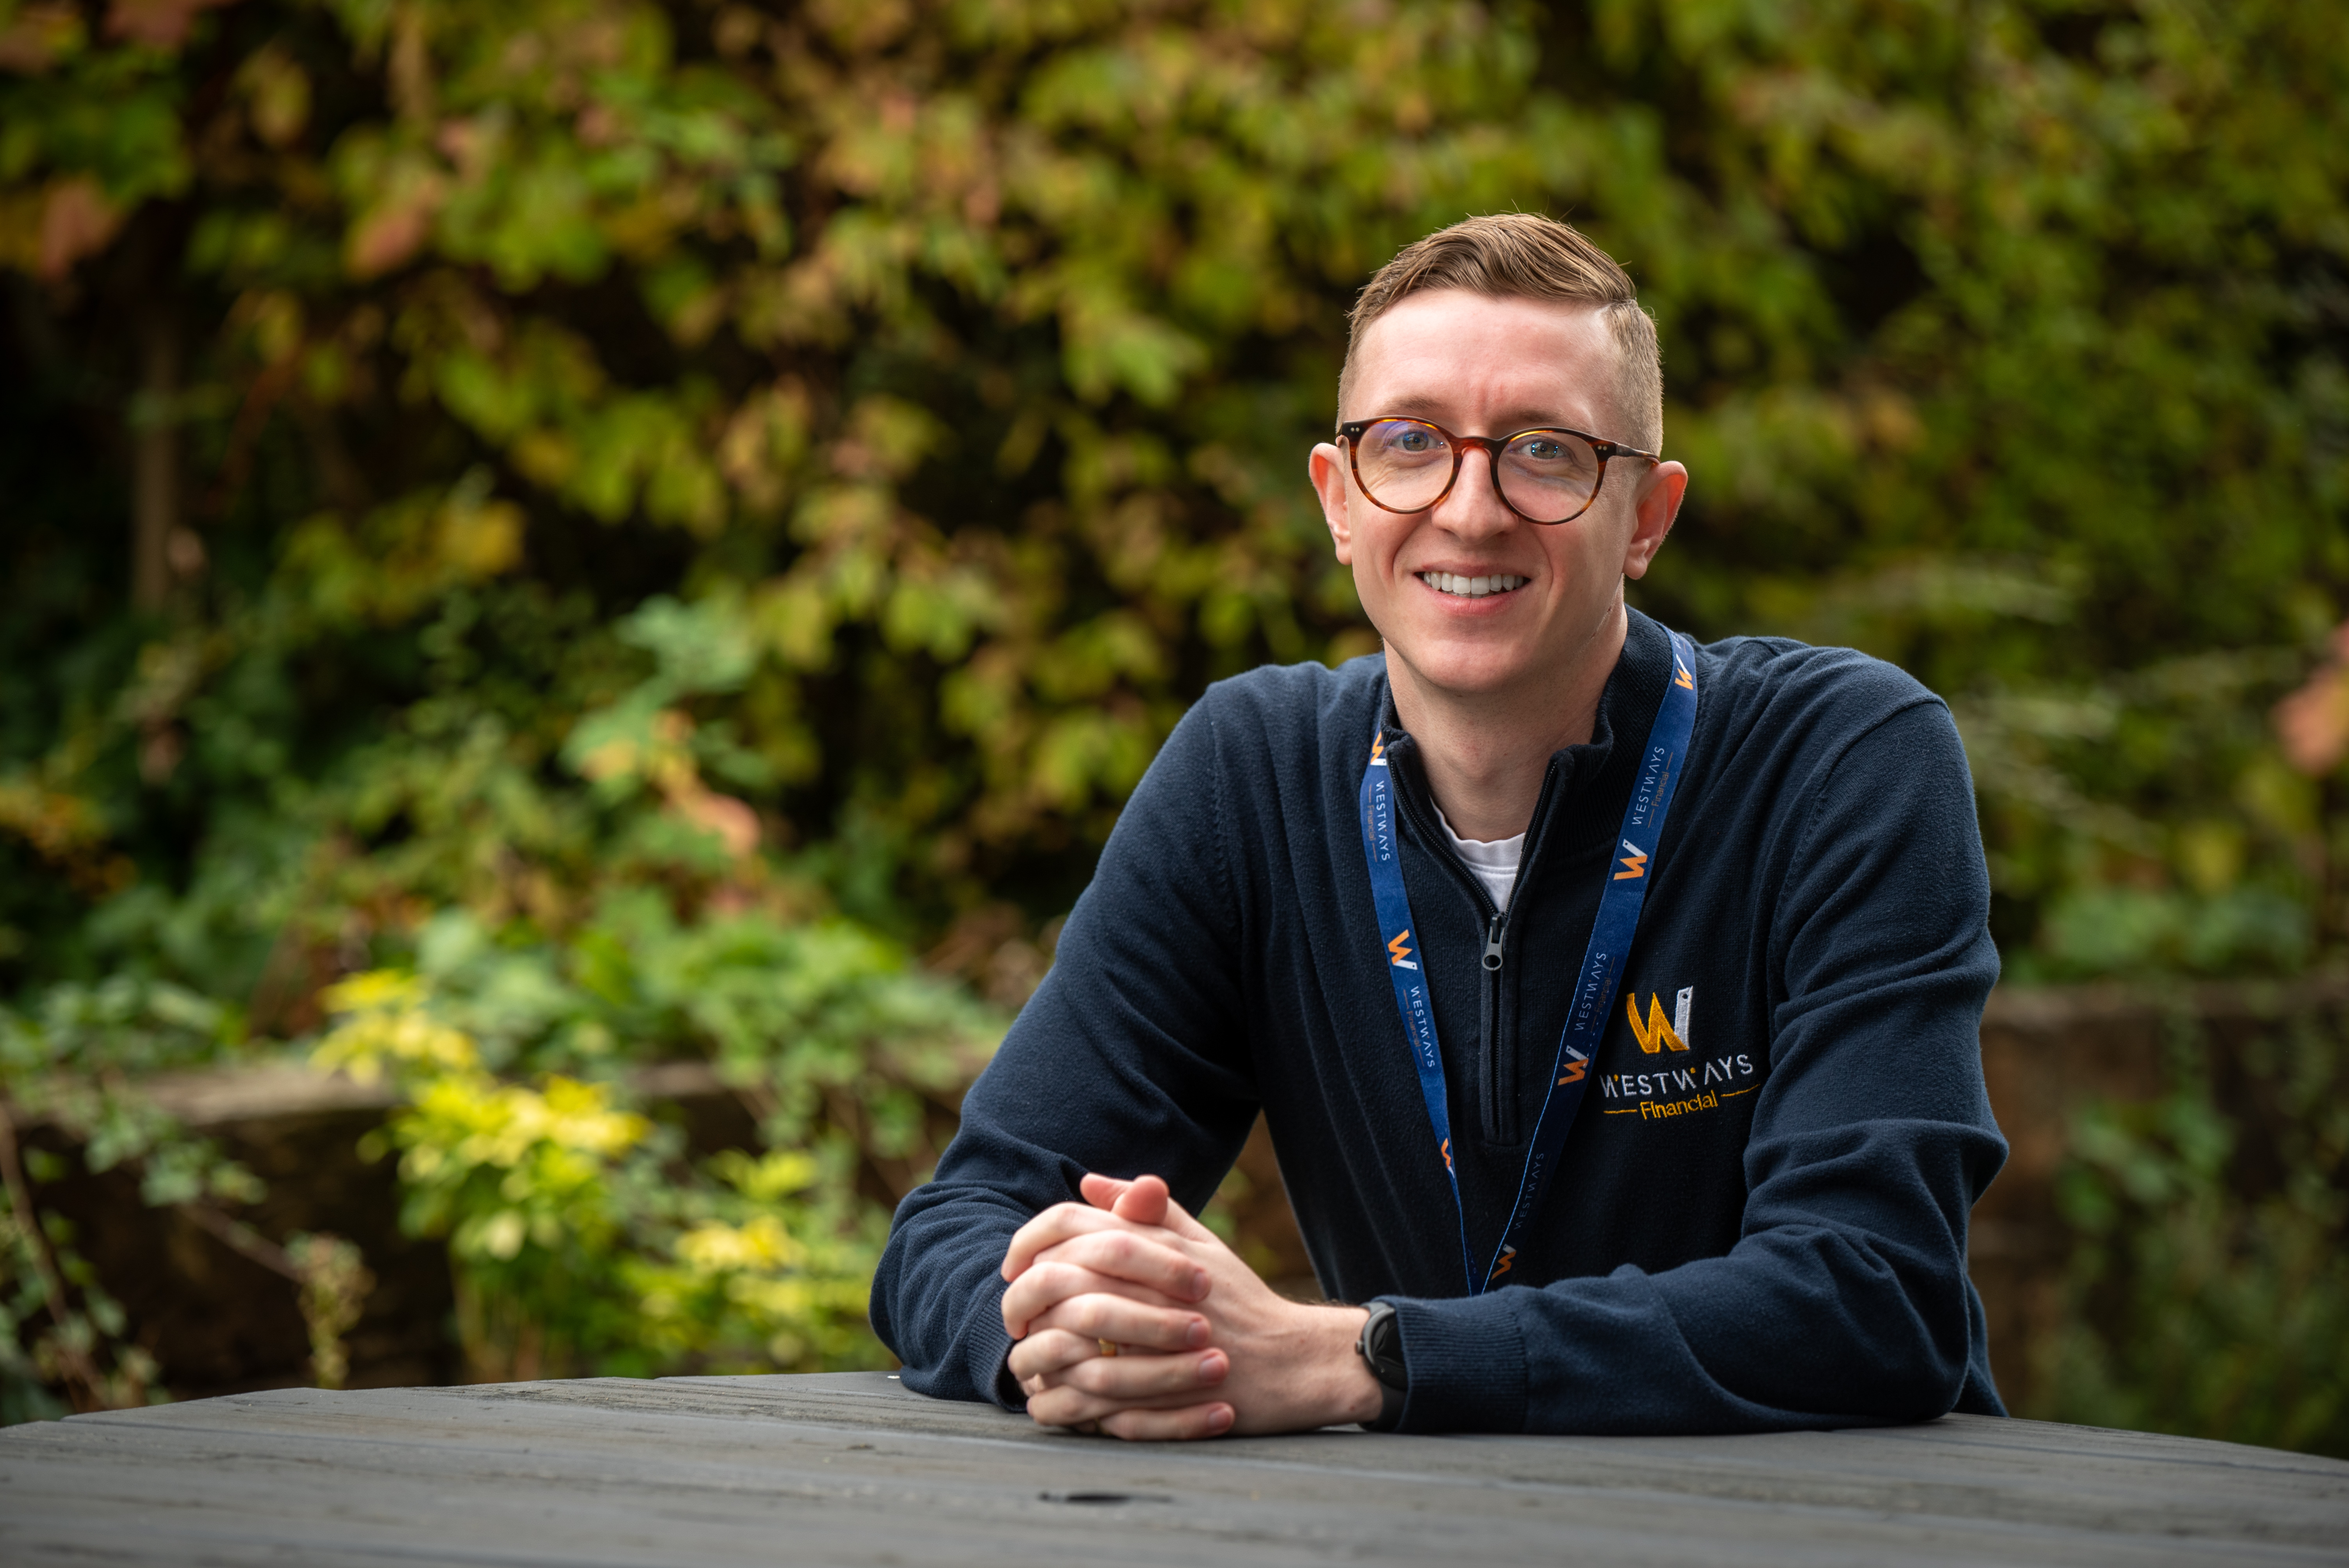
That matters because it points to a wider shift in the industry. Mortgage brokerage is still often seen as a way to access products, yet the reality of borrowing now calls for something more: clear explanation, control of the process and a better sense of what each decision means in the long run. Westways Financial, a family-run brokerage based in Ebbsfleet and serving clients across Gravesend, Dartford and the wider Kent area, offers a useful example of how that model is changing. What makes the firm notable is not simply that it advises on mortgages, but that it has built a more guided and protective service around the mortgage decision itself.
When Access Is No Longer Enough
For a long time, one of the clearest ways for a brokerage to show its value was access: more lenders, more products, more options. That still matters, and Westways has access to more than 96 lenders, but access on its own no longer solves the main problem many clients face. The real difficulty is often making sense of the market. Borrowers are trying to work out lender appetite, affordability rules, credit impact, timing pressures and the balance between an attractive rate now and a mortgage that still suits them later. A mortgage may be tied to one property purchase, but its effects are often felt for years.
That is especially true for the range of clients Westways works with: first-time buyers, first-time sellers, home movers, remortgage clients, borrowers with complex income, people with adverse credit and high-net-worth individuals. These groups may look very different, but they often face the same core issue. They need advice that can turn a confusing market into a decision they feel confident living with, rather than simply a product they can get over the line. That is why the pressure on mortgage firms has changed. The question is no longer only whether they can place a case, but whether they can help clients move through an important financial moment with clarity.
Westways stands out because it approaches that problem through structure. Education, transparency and client understanding sit at the centre of its model, but their value comes from the way they are built into delivery. The firm is organised around the idea that confusion is part of the problem it is there to solve. In a market where stress often builds in the handovers between lenders, solicitors, agents and clients, that becomes a meaningful difference.
A Brokerage Built to Manage the Whole Process
That difference is easiest to see in the way Westways handles advice. It treats mortgage work as a managed process, not just a recommendation. The starting point is a detailed consultation covering income, spending, credit profile, goals and future plans before any advice is given. Research is then shaped around suitability, lender criteria, flexibility and long-term fit, not just headline rates. Once the client agrees a way forward, the firm manages the application, packages the case, deals with lenders and stays in touch with solicitors and estate agents to help keep things moving.
That changes the role of the adviser. Instead of simply opening the door to lenders, the adviser becomes someone who helps organise complexity. For clients, that can mean fewer surprises and less friction at the points where cases often slow down or become hard to follow. For the firm, it creates a stronger form of differentiation than the usual claims of personalised service. The structure itself helps create a smoother experience.
That broader approach also reaches beyond the mortgage itself. Westways carries out protection and will reviews alongside the mortgage process, and includes a complimentary will with every mortgage. That may sound like an added service, but it does something more important than that. It treats buying or refinancing a home as part of a wider question of financial security for the household. This is where the firm’s positioning becomes especially clear. From the start, its aim has been to bring a wealth-management level of advice to everyday property clients. The point is not just that it says this, but that the idea shows up in how the service is built.
Clear Explanation as Part of Good Advice
The same thinking shapes Westways’ education-first approach. In mortgage advice, explanation is sometimes treated as a soft skill, useful mainly because it helps clients feel more comfortable. Here, it plays a more serious role. Clients who understand their options are better placed to make sound decisions, especially when they are buying for the first time or dealing with a more complex case. Confidence is not separate from the outcome. It forms part of the outcome.
That matters even more in the firm’s view that the same standard of advice should apply whether the client is a first-time buyer or a high-net-worth individual. That is a quiet but important shift in emphasis. High-quality advice is being treated as a way of working, not as something reserved for a certain kind of client. In a market where many people still feel rushed, overwhelmed or left to make sense of specialist language on their own, the ability to explain clearly becomes more than a mark of good service. It becomes a real competitive strength.
The family-run nature of the business supports that without needing to dominate the story. Westways describes a culture built around accountability, support and shared values, backed by training, mentorship and consistent internal processes. That matters because it shows how a personal service model can remain reliable as the business grows. The warmth is supported by structure. For smaller advisory firms, that balance is often what separates a genuinely supportive client experience from one that feels inconsistent.
What Westways Says About Brokerage Today
Seen in that light, Westways’ future plans feel less like a set of extras and more like a continuation of the model it has already built. The First Time Buyer Hub, further investment in technology and automation, careful team growth, specialist support for more complex cases and stronger local community engagement all point in the same direction. The firm is trying to grow the clarity and consistency of its service without losing the personal character that helped define it in the first place.
Its growth story supports that reading. Founded in 2021 by two brothers starting from a second bedroom, the business has grown into a team of eight, written more than £139 million in mortgage lending, launched a specialist arm in Port Anchor Financial and built a strong local presence through referrals, community activity, educational content and organic visibility rather than paid advertising. Those details matter not only as achievements, but as signs of a particular kind of business taking shape: one that has grown by turning trust, process and local relevance into a workable advisory model.
That is what makes Westways Financial worth noticing now. It does not represent the whole mortgage market, but it does point to where part of it may be heading. As borrowing decisions become harder to navigate, the firms with lasting value may be the ones that can bring together lender access, clear explanation, process control and wider financial protection in one coherent service. In that sense, Westways is doing more than arranging mortgages. It reflects a broader shift in which brokerage becomes less transactional, more interpretive and, for clients, far more useful.