The Discipline Behind the Five Stars at BVS Mortgages & Financial Services Ltd
For most households, a mortgage begins long before an application form is completed. It begins with a calculation made at a kitchen table, a tolerance for risk quietly assessed against income, dependants and the unpredictability of work. By the time a lender is selected, the decision has already altered the shape of the next twenty or thirty years. The advice that surrounds that commitment influences whether it becomes manageable obligation or latent vulnerability. Since its founding in 2018, BVS Mortgages & Financial Services Ltd has operated inside that moment of consequence, structuring its work around more than rate and approval, and bringing protection into conversations that many borrowers have not previously been encouraged to confront.
The environment in which this advice now sits is shifting. Brokerage growth has accelerated, digital visibility has intensified competition, and regulatory expectations around suitability and protection have sharpened. These pressures reward speed and volume, while the underlying duty remains slow, careful judgement. As firms expand and marketing reach widens, a more searching question emerges: how can advice scale without losing the discipline, clarity and protection focus that long-term borrowing demands? BVS has been building its model around that question, and its results suggest the approach can travel.
Engineering Advice, Not Transactions
The first structural choice BVS makes is to treat the mortgage as a long-term exposure before it becomes a product selection. The process begins with discovery that is deliberately expansive: income, liabilities, dependants, credit profile, affordability headroom, and the client’s longer-term objectives. That early work is not theatrical. It is the discipline that determines whether advice remains suitable when circumstances shift, rates move, or life changes in ways the original application form cannot anticipate.
From there, recommendations are framed as rationale rather than output. Clients are walked through why a lender fits, what the affordability impact looks like over time, and where constraints sit. Protection is not held back as an optional conversation for later. It is embedded as a needs-led discussion around income protection, life cover, critical illness, liabilities and long-term security, anchored in what the household has at stake once borrowing begins. In practice, this approach changes the nature of the client relationship. The borrower is not simply guided to completion; they are equipped to understand the risk they are taking on and the mitigations available, without being forced into jargon or false certainty.
This is where BVS’s positioning becomes tangible. It does not compete on rate as the sole measure of value. It competes on responsibility, clarity and long-term outcome, with protection treated as part of suitability rather than a secondary sales function. In a market that often rewards speed, that choice depends on structure, because it has to be delivered consistently adviser by adviser.
The Operational Architecture Behind the Promise
A protection-embedded approach only holds if the client journey remains coherent when volume rises. BVS has built a structured process that moves from discovery into recommendation and then into execution with fewer handover failures. Once an application is submitted, a dedicated case progression function takes responsibility for lender updates, solicitor liaison, milestone tracking and client communication. That separation matters. It reduces the burden on advisers at the point where many firms become reactive, and it reduces the client’s sense that progress depends on chasing information across multiple parties.
Aftercare is treated as part of service delivery rather than a closing courtesy. Follow-ups and review conversations allow advice to remain suitable as circumstances evolve, and they also reinforce the firm’s commitment to long-term relationship building rather than one-off completion. The client experience is therefore built around continuity: a disciplined journey, supported by specialist operations, with clear communication at each stage.
Digital capability sits inside this structure rather than above it. BVS’s investment in digital systems and an in-house marketing function has strengthened visibility and lead flow, but the more important effect is control. Growth driven through digital reach becomes less volatile when it is matched to an operating model that can handle complexity without losing client care. The firm presents as national in ambition, yet it has organised itself to preserve the feel of a tightly managed advisory practice. BVS Mortgages & Financial Services Ltd is proud to expand its services, now operating under four distinct trade names: BVS Mortgages, BVS Protection, BVS Commercial Finance, and BVS Wealth Management; offering comprehensive solutions for every stage of your financial journey.
Independent Validation as Governance
Independent reviews and awards can be treated as marketing material. They can also be read as a form of external governance when they appear at scale and remain consistent across a team. BVS’s client validation sits in that second category. More than 2,500 five-star Trustpilot reviews and more than 1,500 five-star VouchedFor reviews, alongside rankings in the Best Mortgage Broker category and Top Rated status for advisers, indicate a level of repeatability that is difficult to manufacture. The significance is not the number alone, but what it implies about process discipline across multiple advisers and case types.
This matters because the mortgage and protection market has a persistent credibility problem. Many firms claim client-first ethics, yet few can demonstrate consistency through independent measurement that extends beyond a handful of testimonials. High review volume, when sustained over time, becomes a pressure mechanism on the organisation. It forces the firm to confront variation in service, communication and suitability, because poor advice shows up quickly when clients are encouraged to evaluate the experience publicly and independently.
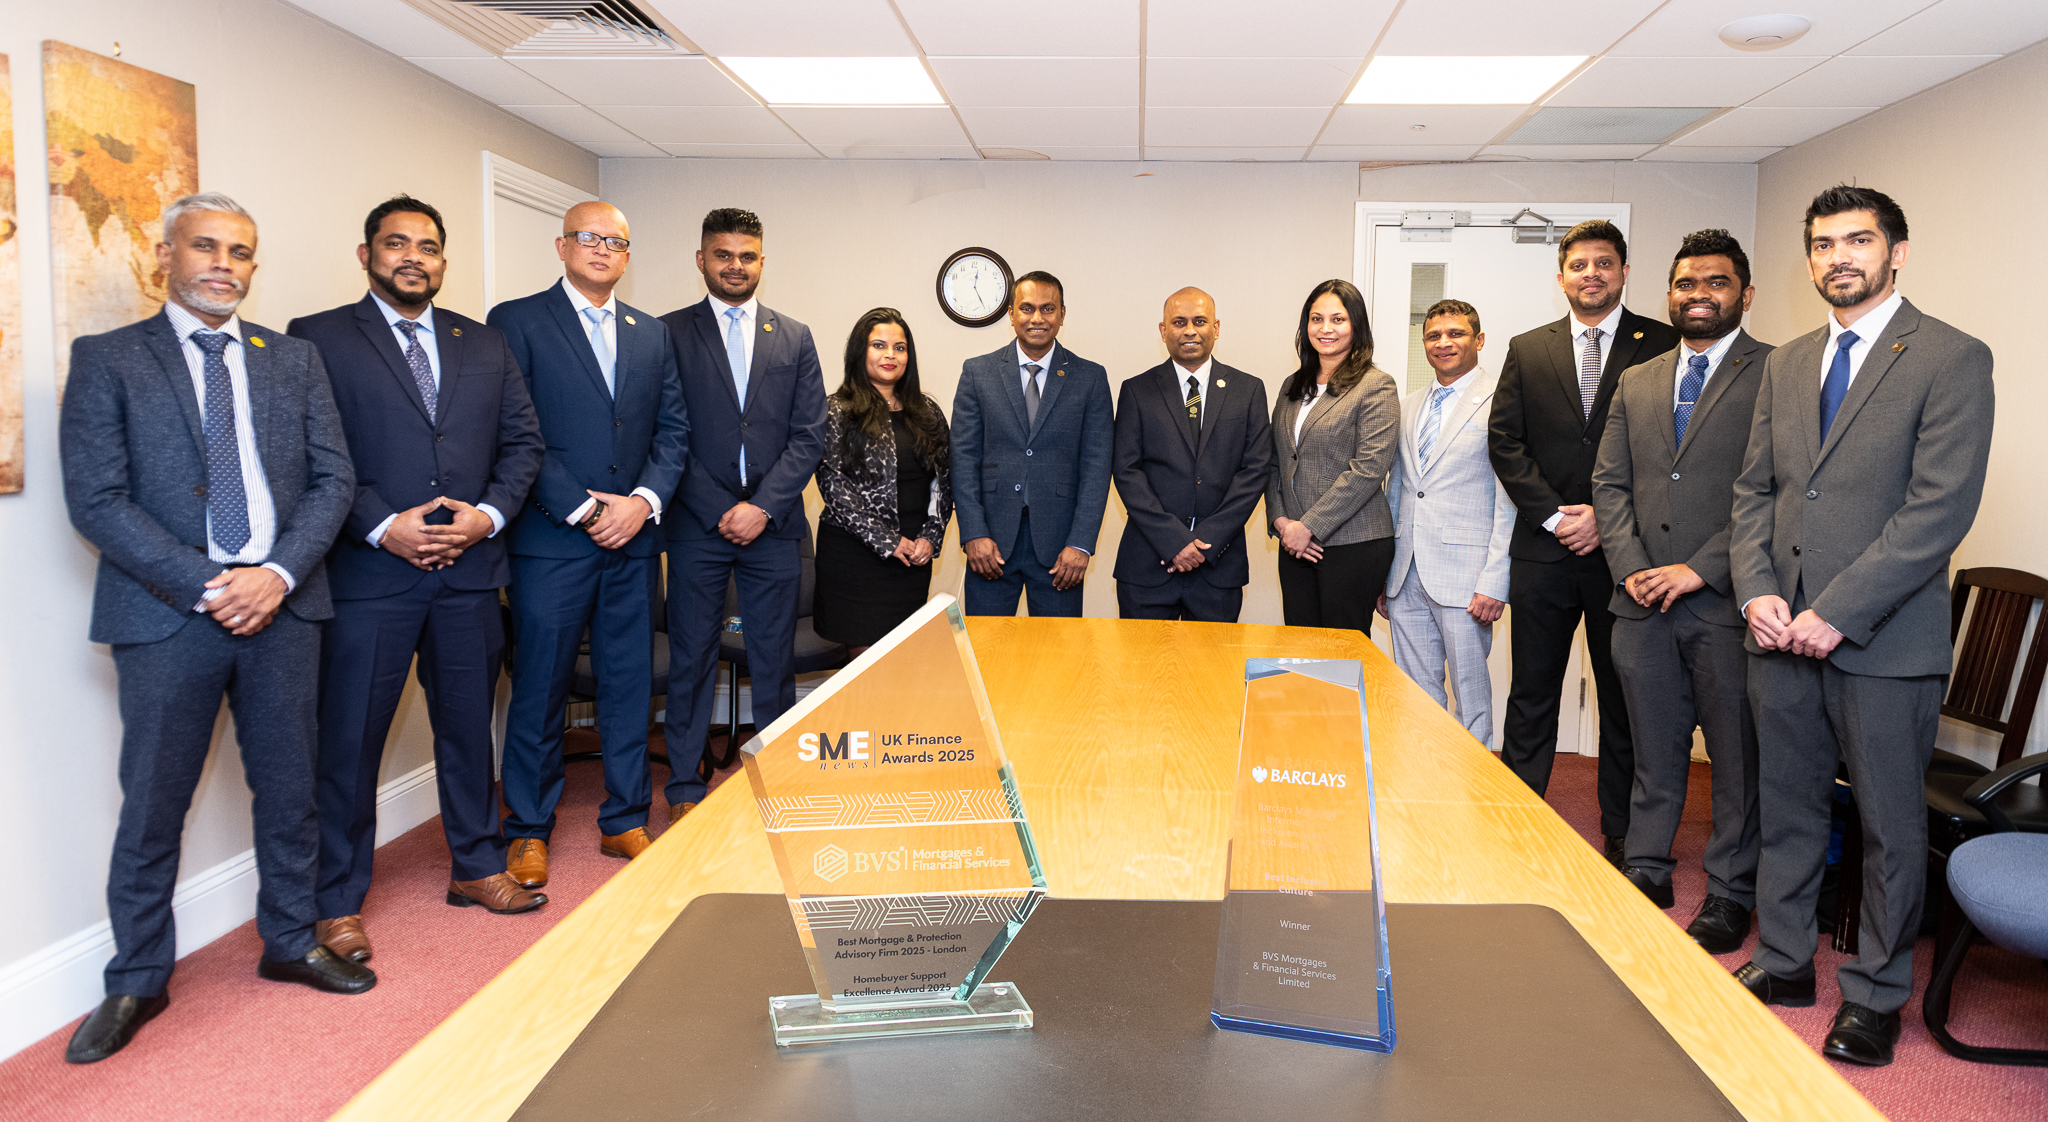
Industry recognition adds a different dimension. Awards for inclusive culture and advisory excellence, together with shortlist positions in broker firm categories, reinforce the sense that BVS’s growth has been accompanied by attention to standards. When read properly, these signals do not substitute for regulatory compliance. They indicate that the organisation has built a culture where accountability is visible, and where performance is expected to be repeatable rather than heroic.
Culture, Leadership and Sustainable Scale
The durability question for any fast-growing brokerage is straightforward. Can it expand adviser capacity nationally without thinning advice quality, weakening protection conversations, or allowing compliance to become a back-office function rather than a discipline embedded in how work is done? BVS has positioned its answer in people development and governance. Continuous professional development frameworks, structured mentoring, and recruitment designed around integrity, resilience and communication are intended to make performance repeatable. Technical skill can be trained. Judgement and client-first behaviour are harder to retrofit, particularly when volume pressure rises.
The firm’s inclusion work, recognised through the Best Inclusive Culture Award at the Barclays Mortgage Intermediaries Inclusion Summit, is described internally as operational rather than symbolic. In practice, that means building environments where advisers are supported and developed, and where opportunity is structured rather than informal. Inclusion becomes part of the way standards are sustained, because it reduces reliance on a narrow set of personalities and allows a larger organisation to maintain coherence.
CSR sits within the same view of durability. Long-term partnership with the EduCare Foundation, continued humanitarian support, and UK-based charity involvement are framed as ongoing commitments rather than periodic campaigns. In a sector that often treats community work as seasonal, the more telling point is consistency, because it reflects leadership discipline and long-term orientation.
Looking forward, BVS’s stated priorities, including expansion of adviser capacity, growth of its commercial division launched in 2025, increased protection penetration, and further automation, read as an attempt to scale without loosening standards. The optimism in this story is not that growth is easy, but that growth can be structured. If the mortgage market continues to reward speed while regulation demands suitability and care, firms will be tested on whether their systems protect clients as reliably as they protect conversion rates. BVS has built its proposition around the idea that advice, when properly engineered, can remain both high-performing and responsible as it expands, and the independent evidence suggests that model is already functioning at scale.